This Issue
August 2026 edition
18.7 km vs 15.0 km a year ago
Median distance from Center City for homes sold as flips, current vs a year ago
Flip volume fell to a two-year low and the trade moved farther from Center City
Flips sold fell to 514 this period, down 37% from 812 a year ago, and the homes that did trade sat a median 18.7 km from Center City, up from 15.0 km. Median sale price held near $335,000, up 3% year over year, but gross margin narrowed to 75.6% of purchase price from 82.5%, suggesting acquisition costs are climbing faster than exit prices. The flip trade is smaller and more suburban than it was twelve months ago.
Investor Playbook
What this issue's numbers suggest checking, by investor type. Observations from recorded data — not investment, legal, or tax advice.
Fewer assignments, bigger spreads
Wholesalers
Recorded assignments ticked up to 7 from 4 last period but remain half of last year's 14, with the median spread rising to $51,250 from $45,000. Worth checking Kingsessing (19143), where flip share of metro activity nearly tripled year over year and flip count (19) led every zip.
The core is thinning, the margin math is tightening
Flippers
Median flip distance from Center City rose to 18.7 km from 15.0 km, and gross margin narrowed to 75.6% of purchase price from 82.5%. Operators with 4-9 lifetime flips post a $196,720 median margin and a 122-day hold versus the market's 209.5 days — the data suggests concentrated, lower-basis buys in zips like Kensington ($75,000 median buy) or Frankford ($105,000) are worth checking against center-city acquisitions.
Hold-strategy formation is outpacing flip formation
Landlords
6,777 buyers added a combined 10,991 units since the last drop, and 13,164 first-time landlords entered the records. 2-4 unit purchases carried a $200,000 median ($125/sqft), well under single-family's $158/sqft — worth checking as flip volume cools and comparable stock may be repricing toward hold buyers.
Recorded volume has consolidated at the top
Private lenders
Recorded private loans fell to 69 from 188 a year ago, with Kiavi, RFLF 4, Const Loan Services and Shallcross capturing most of the recorded volume. The data suggests room in smaller-balance, non-institutional lending outside those top names, particularly where seller financing (median $225,000) is filling gaps.
Larger product still trading despite the flip slowdown
Multifamily investors
Apartment 5+ deals cleared at a $1.6M median ($158/sqft), with this period's largest recorded transactions in West Philadelphia, Burlington and Newark. Worth checking whether cooling flip activity is loosening up 2-4 unit stock at a $200,000 median, a discount to single-family basis.
Factoids
Numbers from this period a practitioner would repeat to a colleague. Each computed directly from recorded instruments.
362 operators — Flippers who closed at least one sale this period
trending down · vs 639 a year ago
The pool of active flip operators shrank by more than four in ten. Fewer players are absorbing the same falling deal count, not a broader base spreading it out.
$196,720 median lifetime margin — Operators with 4-9 lifetime flips
trending up · vs $150,000 median margin for all flips this period
Investors who have done several flips post materially fatter margins and a 122-day median hold, versus 209.5 days market-wide. Repeat, disciplined buying still outperforms one-off flipping.
69 private loans recorded — Private/hard-money loans recorded this period
trending down · vs 188 a year ago
Recorded lending volume dropped by nearly two-thirds even as the median loan size held near $180,000. Institutional funds (Kiavi, RFLF 4) now account for the bulk of what's left.
3.7% of flip volume — Kingsessing (19143) share of metro flip activity
trending up · vs 1.1% a year ago
No other zip moved this much. Kingsessing also led the metro in raw flip count (19) and investor purchases (94) this period.
$160,000 median purchase — Out-of-state buyers (13% of purchases)
trending down · vs $250,000 median for local buyers
Out-of-state capital, led by New York, California and Florida buyers, is concentrated in a lower price band than local investors, not competing head-on for the same product.
$225,000 median note — Seller-financed notes held this period
trending up · vs $180,000 a year ago
Note count fell 23% to 219, but the notes still being written carry a higher median value, pointing to fewer but larger seller-financed deals.
Market Activity — Investor Purchases
Monthly count of investor purchases of MSA properties (left axis) and the median purchase price (right axis), trailing 13 months. The most recent month can grow up to ~15% as late recordings arrive.
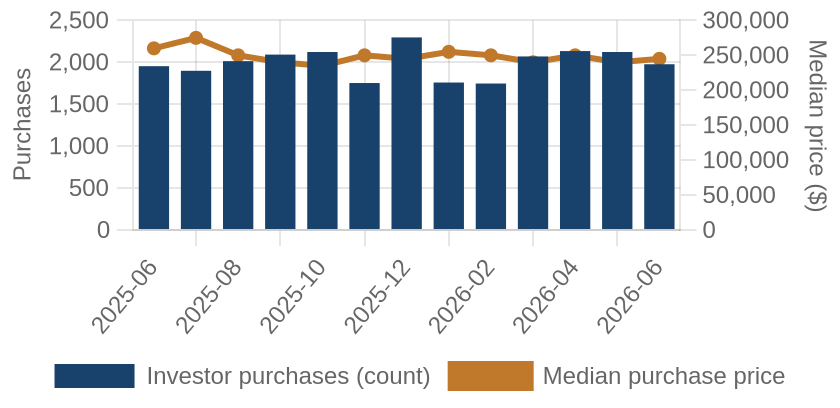
Investor purchases per month (bars) and median purchase price (line), trailing 13 months.
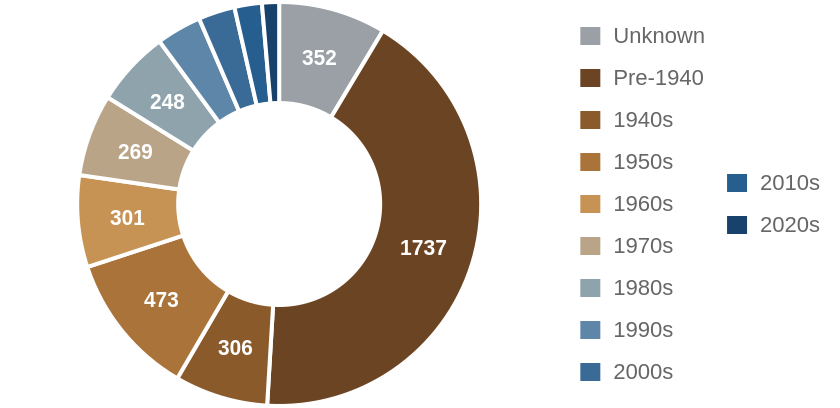
Which vintage of housing investors bought this edition, by decade built.
Where the Money Went
The geography of the period's investor activity: which zip codes saw the most recorded deals, and the largest individual transactions at street level.
The 8 busiest zip codes for investor deals
Pins rank the busiest zips by recorded investor deals (purchases + flips of existing homes) this period — #1 busiest; orange = top 3; pin size scales with deal volume. Median buy is the typical investor purchase; median sale the typical flip resale. Click a pin for details; full table below.
| # | Zip | Area | Purchases | Flips | Median buy | Median sale |
|---|
| #1 | 19143 | Kingsessing | 94 | 19 | $100,000 | $275,000 |
| #2 | 19134 | Kensington | 93 | 9 | $75,000 | $163,000 |
| #3 | 19132 | Strawberry Mansion | 91 | 3 | $47,500 | n/a |
| #4 | 19140 | Hunting Park | 88 | 4 | $67,500 | n/a |
| #5 | 19121 | Brewerytown | 77 | 7 | $120,000 | $165,000 |
| #6 | 19139 | Cobbs Creek | 80 | 3 | $75,250 | n/a |
| #7 | 19124 | Frankford | 77 | 5 | $105,000 | $85,000 |
| #8 | 19013 | Chester | 59 | 4 | $75,000 | n/a |
A representative deal in each of the busiest zips
One deal per zip: the largest matching this market's typical house (typical for this market: 1465 sqft, 3 bed, built around 1953; priced within 4x the county assessment and under 5x its own zip's median).
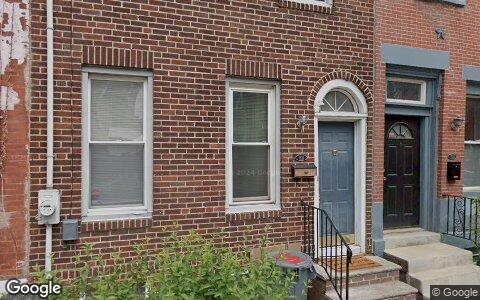
$472,350 · Purchase
1629 W STILES ST, Philadelphia PA 19121
Single family · 1,704 sqft · Jun 30
Street View May 2022 — before the purchase
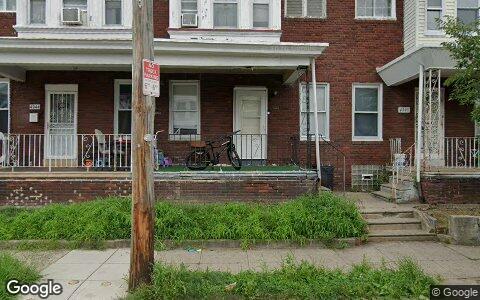
$432,580 · Purchase
4946 CHARLES ST, Philadelphia PA 19124
Single family · 1,080 sqft · Jun 4
Street View Jul 2025 — before the purchase
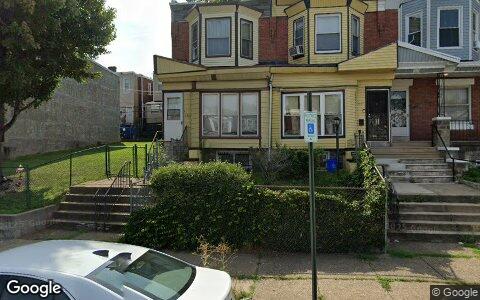
$429,718 · Purchase
5818 WARRINGTON AVE, Philadelphia PA 19143
Single family · 1,208 sqft · May 27
Street View Jul 2024 — before the purchase
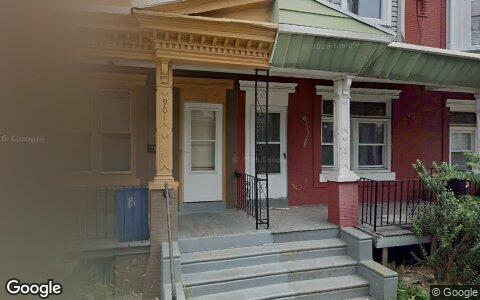
$369,607 · Purchase
107 N RUBY ST, Philadelphia PA 19139
Single family · 1,184 sqft · Jun 3
Street View Jul 2024 — before the purchase
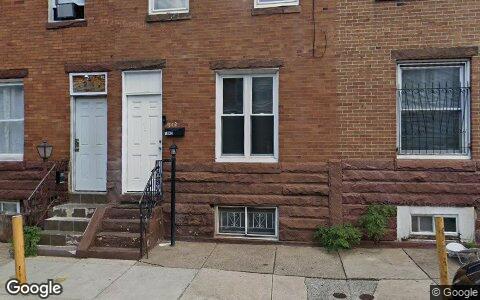
$358,516 · Purchase
1943 E MONMOUTH ST, Philadelphia PA 19134
Single family · 1,214 sqft · May 26
Street View Jul 2025 — before the purchase
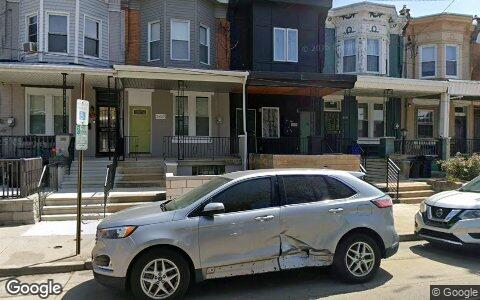
$335,000 · Purchase
3425 OLD YORK RD, Philadelphia PA 19140
Single family · 1,736 sqft · Jun 16
Street View Apr 2025 — before the purchase
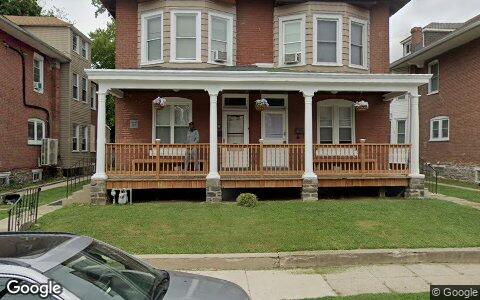
$233,333 · Purchase
38 E 23RD ST, Chester PA 19013
2-4 units · 1,871 sqft · May 27
Street View Aug 2024 — before the purchase
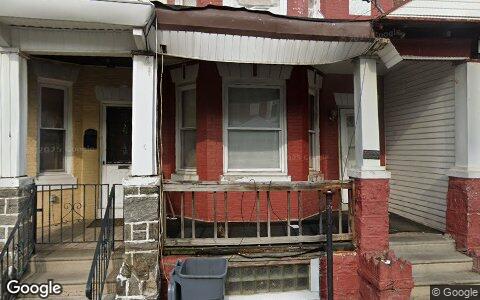
$150,000 · Purchase
2838 N BAILEY ST, Philadelphia PA 19132
Single family · 1,024 sqft · Jun 17
Street View Apr 2023 — before the purchase
Deal sheet — private lending, in date order
Private loans recorded against residential property this period, oldest first.
| Date | Lender | Amount | Property | Use |
|---|
| May 4 | Phoenixville Federal BK&TR | $139,505 | 702 2ND Ave, Royersford PA 19468 | Single family |
| May 5 | Shah Sahil | $200,000 | 4006 Joshua RD, Lafayette Hill PA 19444 | Single family |
| May 5 | Phoenixville Federal BK&TR | $30,000 | 350 King ST, Spring City PA 19475 | Single family |
| May 6 | Gallardo-reza Salvador | $87,292 | 761 Valley RD, Coatesville PA 19320 | Single family |
| May 7 | Township of Abington | $42,650 | 1604 Summit Ave, Willow Grove PA 19090 | Single family |
| May 8 | Splitero Fubding INC | $65,843 | 350 N Fieldstone CT, Yardley DE 19067 | Single family |
| May 8 | Splitero Fubding INC | $65,843 | 350 N Fieldstone CT, Yardley DE 19067 | Single family |
| May 14 | Zunino Edward | $100,000 | 309 Northbank RD, Landenberg PA 19350 | Single family |
Largest flip margin deals of the period, at street level
Gross margin = recorded sale price minus the flipper's recorded purchase price. Purchase deeds are recoverable for roughly 4 in 10 flips; rehab and carry costs are not public record.
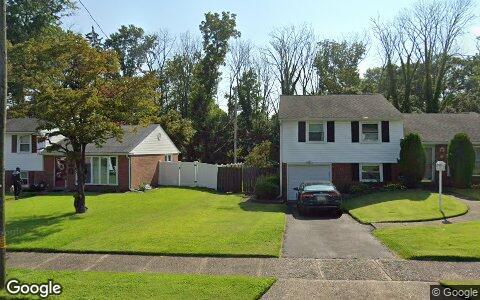
$615,000 gross · bought $485,000 (Dec 2025) → sold $1.1M
310 LEWIS RD, Springfield PA 19064
Single family · 2,094 sqft · Jun 16
Street View Aug 2023 — before the flip (pre-renovation)
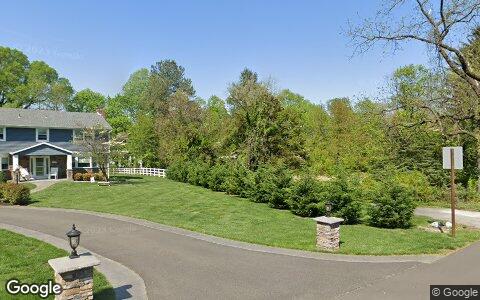
$569,500 gross · bought $200,000 (Mar 2026) → sold $769,500
2716 BRANCH PIKE, Cinnaminson NJ 08077
Single family · 3,134 sqft · Jun 11
Street View Apr 2023 — before the flip (pre-renovation)
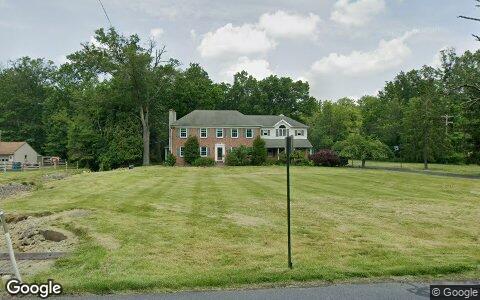
$567,000 gross · bought $593,000 (Sep 2025) → sold $1.2M
1217 MCKEAN RD, Ambler PA 19002
Single family · 3,873 sqft · May 15
Street View Jun 2025 — before the flip (pre-renovation)
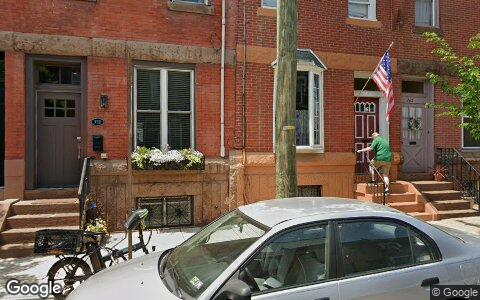
$510,000 gross · bought $400,000 (Aug 2025) → sold $910,000
760 N 23RD ST, Philadelphia PA 19130
Single family · 1,350 sqft · Jun 2
Street View May 2025 — before the flip (pre-renovation)
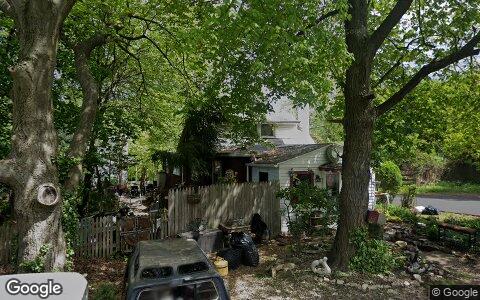
$484,900 gross · bought $225,000 (Dec 2024) → sold $709,900
1941 OAKFORD AVE, Feasterville Trevose PA 19053
Single family · 1,154 sqft · Jun 10
Street View May 2023 — before the flip (pre-renovation)
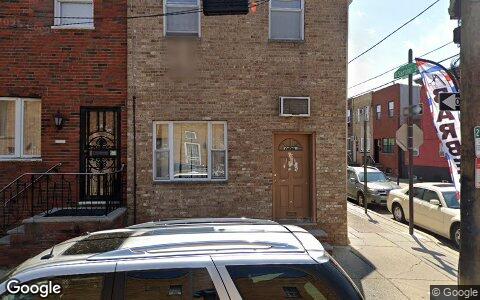
$475,000 gross · bought $295,000 (Nov 2024) → sold $770,000
1126 MIFFLIN ST, Philadelphia PA 19148
Single family · 1,744 sqft · May 7
Street View Apr 2023 — before the flip (pre-renovation)
Flip Structure — Year over Year
How the flip market itself is changing: margins, who is doing the flipping, what they flip, and where. Same two calendar months, this year vs last, from the current data extract.
| Flip market structure | Same months last year | This edition |
|---|
| Flips sold | 812 | 514 |
| Median sale | $325,000 | $335,000 |
| Median $/sqft | $235 | $238 |
| Sale vs county-assessed | 1.82× | 2.06× |
| Median gross margin (matched buys) | $149,950 | $150,000 |
| Median margin % | 82% | 76% |
| Median hold | 6.9 mo | 6.9 mo |
| Homes bought by flippers | 1,059 | 909 |
| Net to inventory (bought − sold) | +247 | +395 |
| Active flippers | 639 | 362 |
| Top-10 flippers' revenue share | 19% | 17% |
| Median house: sqft / beds / built | 1368 / 3 / 1948 | 1374 / 3 / 1948 |
| Pre-1950 stock share | 52% | 51% |
| 2–4 unit share | 9% | 10% |
| Median distance from downtown | 15.0 km | 18.7 km |
Homes bought counts every deed recorded to a known flipper in the window, resold or not. Net to inventory is that minus flips sold. The standing stock is in the Flip Pipeline section.
Attributed profit per flip (per-investor aggregates, by drop period): Feb 26→Jun 26: 1,205 flips, $81,009/flip · Jun 26→Aug 26: 570 flips, n/a (revisions).
County mix (share of flips, last year → this edition): Philadelphia 33%→29% · Camden 15%→15% · Delaware 12%→11% · New Castle 6%→8% · Burlington 8%→8% · Gloucester 7%→7% · Bucks 6%→6% · Chester 3%→5% · Montgomery 7%→5% · Salem 2%→3% · Cecil 2%→2%.
Biggest zip share moves: Kingsessing 1.1%→3.7%.
Flip Pipeline — Buying, Selling and Inventory
Homes bought by known flippers and homes they resold, per month, alongside the stock sitting in flipper hands. A house enters inventory when a flipper buys it and leaves on the next recorded sale, at any price. Purchases still unsold after five years are treated as holds and drop out.
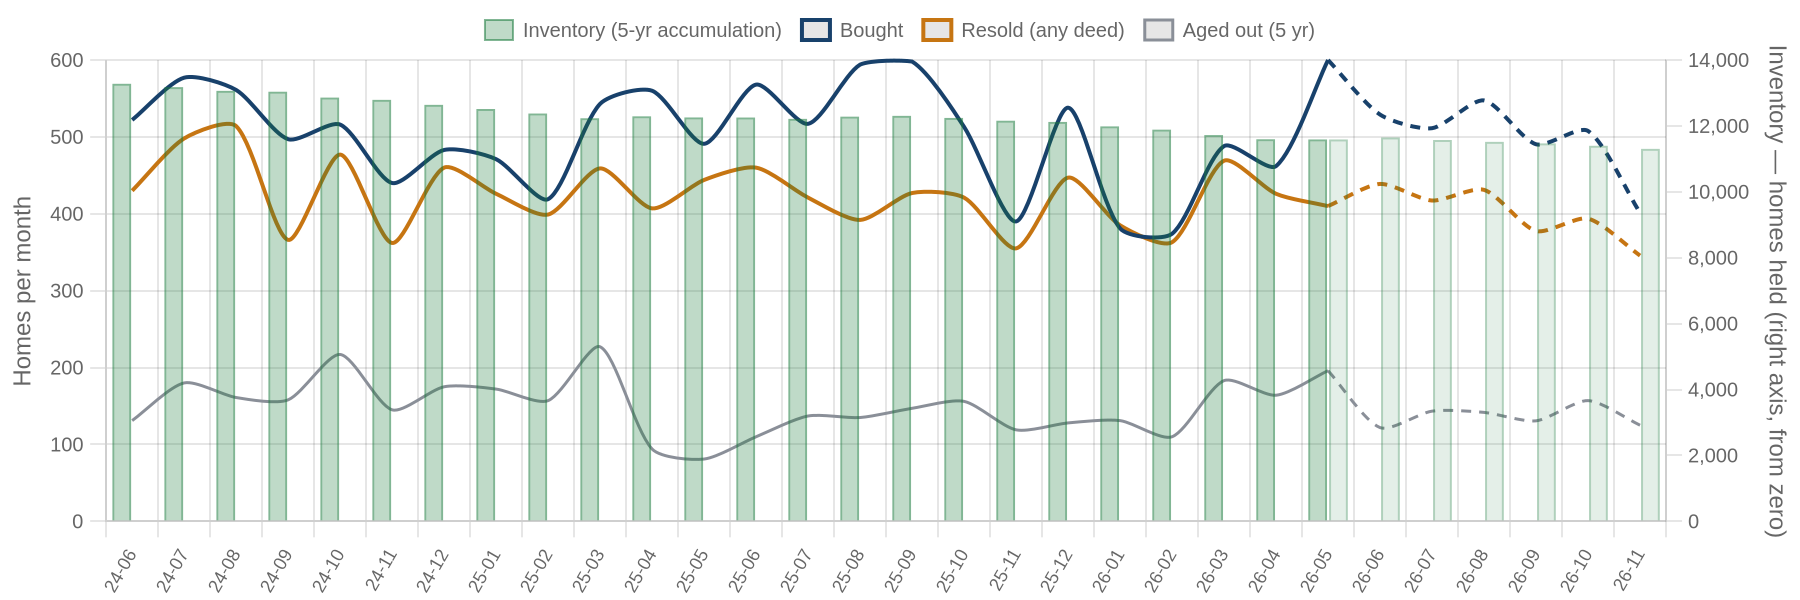
Solid = recorded, dashed = projected. Green bars are inventory on the right axis: homes bought and not yet resold. Aged out is purchases passing five years unsold. Inventory moves by bought minus resold minus aged out.
| Flip pipeline | Bought / mo | Resold / mo | Aged out / mo | Inventory |
|---|
| Latest recorded month (2026-05) | 600 | 410 | 196 | 11,588 |
| Projected (2026-11) | 401 | 346 | 125 | 11,303 |
Method: a straight-line trend through the last 24 months, adjusted for the month of the year, shown dashed as a projection. The series stops before the newest month or two, where deeds are still recording.
Who's Funding the Deals
First mortgages open on flipper purchases from Jul 2025 – Jun 2026 that have not yet resold. 60% carried recorded debt; the rest closed cash or off-record. Ranked by deal count.
60%
Purchases financed
2,338 of 3,873 flipper purchases carried a recorded first mortgage
$223,000
Typical loan
median 1.19× the purchase price — the median lender advances rehab money on top of the buy
67%
Funding the rehab too
1,565 of 2,338 loans exceed the purchase price, so the lender is covering work as well as the buy
| Lender | Loans | Borrowers | Median loan | Loan vs price | Funds rehab | Median purchase |
|---|
| Kiavi Funding INC | 240 | 98 | $262,400 | 1.32× | 91% | $210,000 |
| RFLF 4 LLC | 150 | 46 | $295,250 | 1.29× | 95% | $230,000 |
| Const Loan Services Ii LLC | 114 | 17 | $200,344 | 1.45× | 98% | $140,000 |
| Shallcross Mortgage Company | 61 | 13 | $165,000 | 1.28× | 97% | $120,000 |
| Wells Fargo Bank NA | 42 | 38 | $167,127 | 0.95× | 45% | $172,000 |
| Ifp Fund I LLC | 31 | 19 | $285,000 | 1.48× | 97% | $180,800 |
| Crosscountry Mortgage LLC | 29 | 29 | $299,250 | 0.95× | 17% | $320,000 |
| Loan Funder LLC | 26 | 17 | $252,725 | 1.35× | 77% | $200,000 |
| Genesis Capital | 21 | 4 | $139,500 | 1.72× | 95% | $70,000 |
| Yellow Breeches Capital LLC | 17 | 2 | $440,000 | 1.31× | 100% | $335,000 |
Rates and terms are not published: the county feed models both. Borrowers counts the distinct flippers on each lender's book. Loan vs price is the recorded first mortgage divided by what the buyer paid. Above 1.00x the lender is funding purchase plus rehab; below it the buyer brought cash to the table. Blanket mortgages covering several parcels are excluded, as are loans outside 0.1x-3x the price. Rates and points are not public record.
Flipper Profile — The Working Flipper
The 70th–90th percentile of local flippers by lifetime flip count — the established operators below the whales: 4–9 lifetime flips each. Bath counts are not in the assessor extract.
582
Flippers in the band
each with 4–9 lifetime flips (avg 5.4)
$196,720
Median gross margin
32,407 flips matched to their purchase price
4.0 mo
Typical hold
purchase to resale, matched deals
1465 sqft · 3 bd
Typical house
median year built 1953
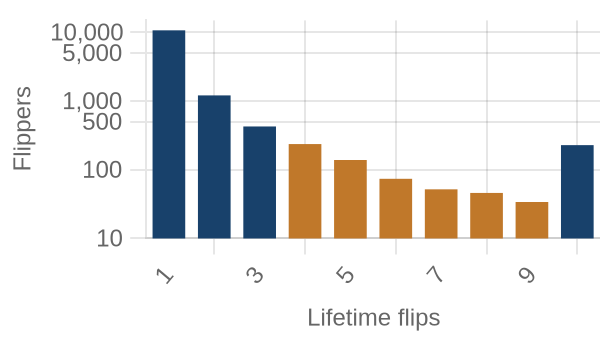
flippers by lifetime flips · orange = this band
Where they work: Pottstown (19464) 2% · Clementon (08021) 2% · Willingboro (08046) 2% · South Philadelphia East (19148) 1% · Williamstown (08094) 1%.
Market Pulse
| per month, Feb–Jun 2026 | per month, Jun–Aug 2026 | change | avg/mo 2yr | avg/mo 4yr |
|---|
| ▼ Homes bought by flippers | 530 | 455 | -14% | 504 | 532 |
| ▼ Flips sold (deeds) | 406 | 257 | -37% | 426 | 464 |
| ▲ Lending deals funded | 123 | 466 | +279% | — | — |
| ▲ Seller/notes held (net) | 14 | 108 | +94/mo | — | — |
| ▼ Investors (net) | -773 | -5,476 | −4,703/mo | — | — |
Flips and flipper purchases = recorded deeds, same two months each year; their 2- and 4-year columns are per-month averages of the deed series. The remaining rows come from the investor file, which spans 13 months, so they have no multi-year average (2026: Jun 2026 → Aug 2026; 2025: Feb 2026 → Jun 2026).
Past Issues
Methodology
Source Data
County recorder & assessor via FARES
Every figure is computed from recorded instruments (deeds, mortgages, assignments) and assessor property records for the five counties of the Philadelphia-Elyria MSA. No surveys, no estimates, no listings data.
This edition analyzes transactions dated May 1 – June 30, 2026, as recorded through the 2026-08 data extract.
Who Counts as an Investor
Transaction-pattern identification
Investors are entities whose recorded transaction history looks like investing: rental holding (landlords), short-hold resales (flippers), private mortgage lending, note holding, or contract assignment (wholesalers). Banks, homebuilders, iBuyers, SFR funds, and government entities are identified by name and reported separately from small investors.
How Comparisons Work
Attribution deltas + same-window comparisons
The Market Pulse reports activity attributed between successive data drops, from the per-investor lifetime totals maintained upstream — periods differ in length, so per-month rates are shown. Elsewhere, "vs. year ago" compares the same calendar months one year earlier, counted from the same data extract. Transfers under $5,000 (quitclaims, partial interests) are excluded everywhere. Counts lag recording by 4–8 weeks, and the newest month can grow up to ~15% as late records arrive — direction is reliable before magnitude.
Known Limits
Floors, not ceilings
Wholesale assignments only appear when they touch a recorded deed, so those counts are a floor. Flip hold times are measured from the prior recorded sale. Names are the owner of record, which may be an LLC or trust.
About
Purpose
A working tool for small real estate investors in Greater Philadelphia: what actually closed, where, at what prices, and what it suggests checking next — one theme per issue.
Cadence
Published with each bi-monthly data drop, covering the two most recent complete months of recorded activity.
Disclaimer
Observations from public records, not investment, legal, or tax advice. Past activity does not guarantee future results. Verify any property or counterparty independently before transacting.